What is the scope and industry significance of the White Coal Market?
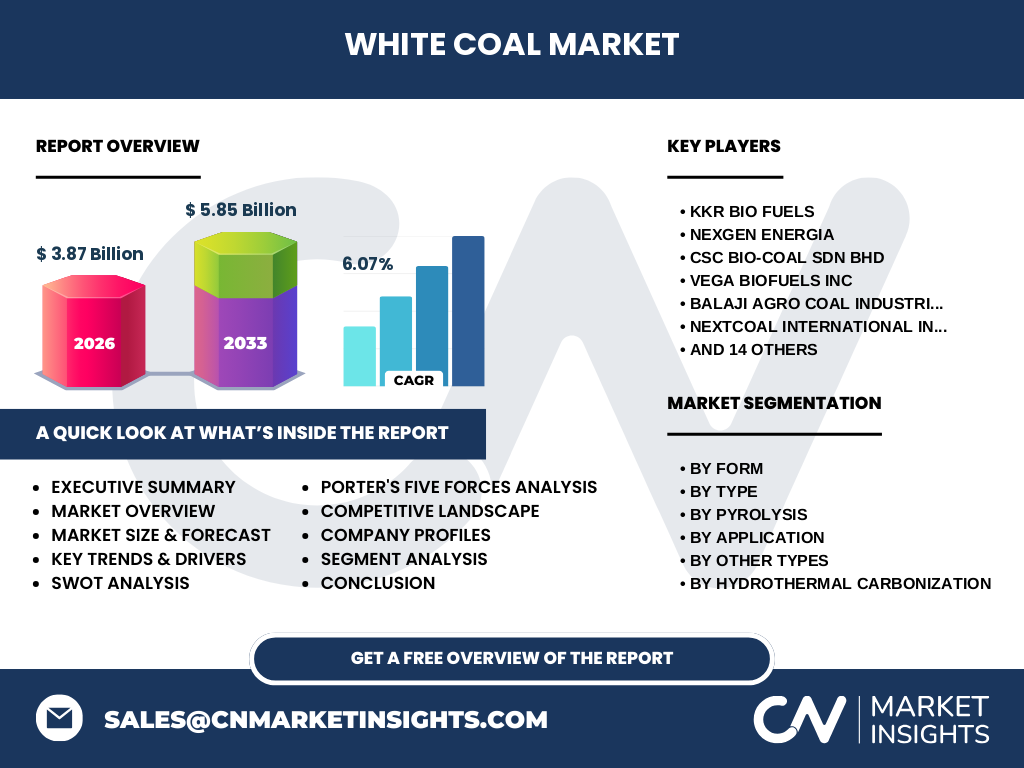
The White Coal Market represents a critical paradigm shift in sustainable energy, valued at 3.87 Billion in 2026. Our analysis indicates that this sector transforms agricultural residues and forestry waste into high-density, eco-friendly biomass briquettes, pellets, and logs, serving as a vital direct-replacement fuel for carbon-intensive thermal coal across heavy industries.
Structural Growth Drivers, Restraints, and Opportunities in the White Coal Market
Stringent environmental mandates by bodies like the International Energy Agency and national carbon taxation act as primary catalysts for the White Coal Market. Conversely, raw material price volatility poses restraints. However, massive opportunities emerge in co-firing applications within pulverized coal-fired utility boilers, enabling legacy power producers to meet strict decarbonization targets cost-effectively.
Emerging trends and growth patterns in White Coal Market
The White Coal Market industry trends highlight an accelerated transition toward advanced thermal conversion technologies. Industrial end-users increasingly demand torrefied biomass and hydrothermal carbonization products that offer higher energy density and superior moisture resistance, closely mirroring the combustion profile of traditional fossil coal without the associated net carbon emissions.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe supply chain disruptions across the White Coal Market, delaying critical greenfield plant installations and stalling agricultural waste collection logistics. However, the post-pandemic recovery trajectory has been exceptionally robust, fueled by aggressive government stimulus packages prioritizing green industrial transitions and mandatory industrial decarbonization frameworks.
Competitive Benchmarking: Major Players and Market Dynamics
The White Coal Market features a moderately fragmented competitive landscape characterized by specialized technology providers and regional agro-pellet manufacturers. Industry leaders such as Drax Group plc and Vow ASA leverage proprietary thermal processing patents to secure long-term offtake agreements with major energy conglomerates, establishing significant entry barriers for smaller local operators.
Executive summary of key findings about White Coal Market
Driven by robust sustainability mandates, the White Coal Market size is projected to expand to 5.85 Billion by 2033, exhibiting a solid CAGR of 6.07% from 2027. Our research concludes that technological advancements in torrefaction and gasification will unlock unprecedented adoption rates across traditional high-emission sectors.
Market forecast from 2027 to 2033
Our proprietary financial modeling projects that the White Coal Market analysis will achieve a steady CAGR of 6.07%, scaling from 3.87 Billion in 2026 to reach 5.85 Billion by 2033. This sustained upward trajectory is underpinned by mandatory coal-phaseout timelines enacted by regulatory authorities across developing and developed economies alike.
Segmentation analysis across forms, types, and applications
The White Coal Market is structurally segmented by form (briquettes, powder, logs, other forms), type (pyrolysis, hydrothermal carbonization, gasification, torrefaction, briquetting), and application (ceramic, chemical, food and beverage, textile, power, other applications). Briquettes and Pyrolysis-based variants currently dominate volume share due to their seamless integration into existing industrial boiler architectures.
Regional market analysis and geographic performance
Geographic performance within the White Coal Market heavily mirrors regional agricultural output and air quality regulations. Asia-Pacific leads consumption due to massive agricultural residue availability and stringent government bans on crop residue burning, while Europe maintains dominance in advanced torrefied biomass adoption driven by stringent carbon trading schemes.
In-depth regional review of high-growth territories
Regional deep-dives reveal that developing economies in South and Southeast Asia represent the fastest-growing pockets within the White Coal Market, propelled by localized policy incentives for agro-waste recycling. Meanwhile, North American markets focus on industrial-scale co-firing, supported by established forestry supply chains and carbon capture tax credits.
Strategic positioning of leading companies in White Coal Market
Industry pioneers like Airex Energy Inc and TorrCoal focus heavily on proprietary torrefaction intellectual property to deliver hydrophobic, high-calorific biomass. Concurrently, regional players such as Lehra Fuel Tech Pvt Ltd and Balaji Agro Coal Industries capture significant localized market share by manufacturing robust briquetting machinery tailored for decentralized agricultural clusters.
Porter's Five Forces analysis of competitive pressures
In the White Coal Market, supplier power remains moderate due to fragmented agricultural waste sources, whereas buyer power is high as industrial clients demand stringent calorific consistency. The threat of substitutes is mitigated by carbon tax penalties on fossil coal, though capital intensity creates a moderate barrier against new entrants.
SWOT analysis of the White Coal sector
Key strengths of the White Coal Market include carbon-neutral energy profiles and waste-to-wealth utility. Weaknesses involve high initial capital expenditure for advanced pyrolysis plants. Opportunities lie in chemical industry feedstock diversification, while severe threats stem from unpredictable seasonal availability and moisture degradation of raw biomass feedstocks.
Value chain analysis from raw materials to end-users
The White Coal Market value chain initiates with agricultural and forestry residue aggregation, progressing through mechanical densification or thermal refinement via pyrolysis and hydrothermal carbonization. Finished products transit via maritime and rail logistics to power utilities, textile plants, and ceramic kilns, ensuring localized economic multipliers.
Strategic investment insights and high-potential areas
Investors evaluating the White Coal Market should prioritize high-temperature hydrothermal carbonization technologies and automated briquetting facilities located near dense agricultural hubs. Strategic partnerships with multinational logistics providers offer distinct competitive advantages in securing uninterrupted, low-cost biomass feedstock supply chains.
Conclusion and key takeaways for stakeholders
The White Coal Market transitions from an alternative fuel novelty to an indispensable industrial decarbonization pillar, supported by a projected 5.85 Billion valuation by 2033. Stakeholders must embrace advanced thermal upgrading technologies to capture premium margins and future-proof their operations against tightening environmental regulations.
Research methodology and data triangulation
Our analysis for this White Coal Market report relies on rigorous data triangulation, combining primary stakeholder interviews with C-suite executives, exhaustive secondary trade registry data, customs clearing reports, and macroeconomic energy consumption indicators to establish reliable baseline estimates and forecast metrics.
Scope of the report, coverage parameters, and limitations
This comprehensive report evaluates the global White Coal Market across key technological variants, application verticals, and geographic regions from 2026 to 2033. Limitations include potential unforeseen macroeconomic disruptions and localized policy reversals regarding agricultural subsidy frameworks and carbon pricing mechanisms.
Recent developments, company announcements, and strategic moves
Recent strategic maneuvers in the White Coal Market include Drax Group plc expanding its international sustainable biomass sourcing footprint, and Vow ASA deploying advanced pyrolysis reactors for industrial clients. These moves underscore an industry-wide pivot toward high-efficiency, localized conversion infrastructure and long-term corporate supply agreements.